
What Percentage of a Nonprofit Budget Should Be Fundraising?
What percentage of a nonprofit budget should be fundraising? Use this practical guide to evaluate costs, revenue mix, board oversight, and mission impact.
Fundraising is an investment in your nonprofit’s ability to deliver its mission, not simply an expense to minimize. The right budget depends on where your organization is growing, how it brings in revenue, and what it takes to build lasting donor and community relationships.
There is no universal answer to what percentage of a nonprofit budget should be fundraising. Instead, evaluate the full cost of fundraising alongside revenue mix, program stage, channel performance, staffing capacity, and the outcomes your work supports.
Join the Bike to the Beach community and connect with mission-driven nonprofit work
Before reviewing ratios or benchmarks, start by defining what belongs in the fundraising line and how it relates to the rest of your operating plan. That shared language gives leaders, finance teams, and boards a clearer foundation for thoughtful budget decisions.
What Does Fundraising Mean in a Nonprofit Budget?
Fundraising expense is the cost of building and maintaining the revenue that supports a nonprofit’s mission. It can include development staff time, donor communications, event costs, software, payment processing, campaign materials, stewardship, and the share of facilities or technology used for fundraising. The right classification depends on how your organization tracks costs and what each expense helps accomplish.
Direct program expenses are costs tied to delivering a specific service or activity. For example, a therapy program may assign facilitator wages, supplies, and program transportation to that program. Management and general expenses support the organization as a whole, including finance, governance, human resources, insurance, and general administration.
Overhead is often used as a broad category that combines management and general expenses with fundraising expenses. Direct program costs are generally treated separately. That distinction matters because a low overhead figure does not automatically mean a nonprofit is effective, and a higher figure does not automatically signal waste. Some administrative spending builds the capacity needed to manage programs, meet reporting obligations, and grow future revenue.
The Association of Fundraising Professionals explains that a fundraising cost ratio compares fundraising spending with money directed to charitable programs. It also cautions that relying on one ratio can be too simplistic. When reviewing a budget, look at the full story:
- Which costs generate, steward, or retain revenue?
- Which costs deliver services directly to participants or communities?
- Which shared costs keep the organization accountable and capable?
- How do these investments support the mission over the period being reviewed?
Classifying expenses clearly helps leaders compare actual spending with the approved plan, explain tradeoffs to the board, and evaluate fundraising in context rather than chasing an arbitrary percentage.
What percentage of a nonprofit budget should be fundraising?
There is no universal percentage that every nonprofit should spend on fundraising. A useful budget depends on the organization’s mission, stage of development, revenue mix, fundraising methods, and capacity to deliver its programs. A low fundraising allocation is not automatically efficient, and a higher allocation is not automatically wasteful.
The Association of Fundraising Professionals (AFP) explains that fundraising cost needs context. Organization type, program maturity, the role of government funding, and reliance on expensive activities such as direct marketing or special events can all affect what an appropriate investment looks like. AFP also cautions that a fundraising cost ratio is only one indicator, not a complete measure of organizational effectiveness. Read its context on what fundraising should cost.
The table below is a planning lens, not a benchmark or a recommended ratio. Use it to ask better questions before setting a number.
| Planning factor | What changes | What to review |
|---|---|---|
| Organization stage | Newer or growing organizations may be building donor relationships, systems, and a reliable pipeline. | Are current investments building durable revenue and supporter trust? |
| Revenue mix | Government funding, grants, individual gifts, sponsorships, and earned revenue create different fundraising demands. | Which sources require active cultivation, and how concentrated is the revenue base? |
| Fundraising channel | Direct marketing, digital outreach, major gifts, grants, and events carry different staffing and operating needs. | What are the fully loaded costs and outcomes for each channel? |
| Event strategy | Special events can support visibility and relationships while also requiring planning, logistics, and staff time. | Does the event advance the mission and strengthen the broader fundraising program? |
Instead of asking whether a single percentage is correct, compare the investment with the revenue it supports, the relationships it builds, and the mission outcomes it makes possible. Review the assumptions regularly as the organization and its funding environment change.
How Should a Nonprofit Calculate Fundraising Investment?
A useful calculation starts with a clear question: what are you measuring, and what decision will the result support? A fundraising percentage can help organize a budget, but it should not replace context about revenue sources, program commitments, or the time required to build durable donor relationships.
- Define the denominator. Decide whether you are comparing fundraising costs with total expenses, total revenue, contributions, or a specific fundraising program. Record the choice in your budget notes and use the same definition when comparing periods. Keep fundraising expense distinct from direct program costs and other management expenses so the result is understandable to staff and board members.
- Map fully loaded fundraising costs. Include more than campaign materials or event fees. Add relevant staff time, technology, processing, communications, training, contractor support, and shared costs that genuinely support fundraising. Separate one-time investments from recurring costs, since a new system or campaign may serve future periods as well as the current one.
- Compare the approved budget with actuals. Build a simple variance view for each fundraising activity: budgeted cost, actual cost, budgeted revenue, actual revenue, and timing. RENOSI’s nonprofit budget example separates revenue and expense lines before comparing actual income and expenses with the approved budget. Review its approach, then share nonprofit financial context in a format your stakeholders can follow.
- Review the revenue mix. Look at which activities generated unrestricted gifts, restricted support, sponsorship, event income, or in-kind help. Consider whether a channel is acquiring new supporters, renewing existing ones, or advancing a longer-term relationship. Avoid averaging unlike activities into one number that hides important differences.
- Set one next-period test. Choose a specific improvement to evaluate, such as clearer stewardship for renewing donors, a revised event workflow, or better tracking of volunteer time. Define the cost, expected learning, review date, and measures of success before spending. At the next budget review, compare the test with its actual results and its effect on mission capacity, not just its fundraising ratio.
This process turns the question of what percentage of a nonprofit budget should be fundraising into a repeatable planning exercise. The goal is a transparent, evidence-led investment decision that can improve over time.
Which Factors Change a Reasonable Fundraising Budget?
A reasonable fundraising budget reflects the work required to build and sustain revenue, not a fixed share that every nonprofit should copy. The right planning context depends on where the organization is in its lifecycle, how it raises money, and what capacity it can support responsibly.
Organizational stage and scale
A newer organization may need to invest in basic systems, donor records, message development, and relationship building before its results resemble those of a mature fundraising program. A larger organization may have more specialized staff and established processes, but it may also manage more complex campaigns and reporting needs. Size, total budget, and the maturity of the organization and its development function can all affect fundraising costs.
Revenue mix and channel economics
Different revenue sources require different kinds of work. Major gifts, grants, recurring giving, direct response, sponsorships, and events each involve distinct research, stewardship, technology, and communications. A channel that looks efficient in one period may be in an acquisition or testing phase in another. Review results by channel instead of blending every expense into one headline ratio.
That review should include the people and tools behind the work. Staff time, volunteer involvement, training, data management, creative production, payment processing, and event logistics can change the fully loaded cost. The cost of volunteer-supported work may look different from a staff-led campaign, but volunteer capacity is not unlimited or free of coordination needs.
Geography, events, and timing
Regional reach, travel, local partner relationships, venue requirements, and event complexity can all reshape the resources a campaign needs. Events may also have a different cost pattern from year-round donor stewardship. Compare a channel across an appropriate averaging period, and account for startup or one-time investments rather than judging one unusual month in isolation.
For example, organizations with substantial matching-gift potential may want to evaluate matching gift workflows before assuming the answer is simply to spend more. The strongest budget is the one that matches capacity, revenue strategy, and mission goals while leaving room to learn.
How Can Nonprofits Evaluate Whether Fundraising Spending Works?
Cost to raise a dollar can help a nonprofit see how much fundraising expense supports each dollar brought in. It is useful for comparing similar campaigns over time, but it is not a complete scorecard. Results can vary by fundraising method, organizational maturity, revenue source, volunteer involvement, and the period being measured. A low cost alone does not prove that a program is healthy, just as a higher cost in a growth period does not automatically mean the investment failed.
Build a wider dashboard around several complementary measures:
- Return rate: Compare revenue with the expense of the specific fundraising effort, while labeling whether the calculation uses gross or net revenue.
- Average gift: Track whether the typical contribution is growing, stable, or shrinking by channel and donor group.
- Cost per gift: Pair total fundraising expense with the number of gifts received. This can reveal changes that a broad organization-wide ratio hides.
- Donor retention: Review how many donors continue supporting the organization in a later period. Strong short-term revenue is less useful if the experience drives supporters away.
- Donor experience: Consider response time, clarity of communications, ease of giving, and whether supporters understand what their contribution makes possible.
These measures should be read together, not ranked in isolation. A campaign may produce modest first-period returns while introducing new supporters, strengthening relationships, or creating a reliable renewal pipeline. Conversely, a campaign that looks efficient on paper may require staff effort that limits other revenue or program work.
Finally, connect financial measures to mission outcomes. Ask whether the funds supported planned services, reached intended communities, and produced results the organization can explain honestly. Reviewing measure nonprofit program impact can help boards and staff connect fundraising decisions with the people and programs they exist to serve.
How Should Boards Review Fundraising Budget Decisions?
Board review works best as an ongoing conversation about mission, capacity, and risk, not a one-time vote on a percentage. Start with the annual budget and program plan. RENOSI identifies board approval of those plans as an important responsibility for nonprofit groups, and the approval should make the fundraising assumptions visible alongside program goals: expected revenue, planned expenses, staffing, events, and timing.
After approval, give the board regular actual-versus-budget reports. A useful report shows where revenue and fundraising expenses stand against plan, explains meaningful variances, and distinguishes timing differences from a change in outlook. The RENOSI budget example separates revenue and expense lines before comparing actual results with the approved budget. That structure gives directors enough context to ask whether a shortfall calls for a revised forecast, a new fundraising test, or a deliberate program adjustment.
Scenario review adds another layer of resilience. Discuss a base plan, a slower-revenue scenario, and a growth scenario. For each, identify which activities could be delayed, which commitments are essential, and what additional fundraising capacity would be required. Consider risks such as dependence on one revenue source, an event that underperforms, staff turnover, or restricted funds that cannot support general operations. Avoid treating one cost ratio as a complete verdict on effectiveness.
Helpful board questions include:
- What assumptions support this fundraising plan, and which are most uncertain?
- What did actual results teach us about timing, channel performance, and donor response?
- Are we investing enough to protect fundraising capacity and program quality?
- What would we change if revenue came in below plan?
- How will we report the connection between fundraising activity and community impact?
Boards can strengthen nonprofit board oversight by pairing financial review with clear governance roles, documented decisions, and respectful challenge. A well-structured annual report can also help organizations share nonprofit financial context with supporters and partners.
How Can Fundraising Support Local Community Impact?
Sustainable fundraising is more than a way to close a budget gap. It can help a nonprofit build relationships with local partners, invite community participation, and fund services that reflect the needs of the people it serves. The strongest approach connects the money raised to a clear impact story without treating one organization’s model as a universal budget rule.
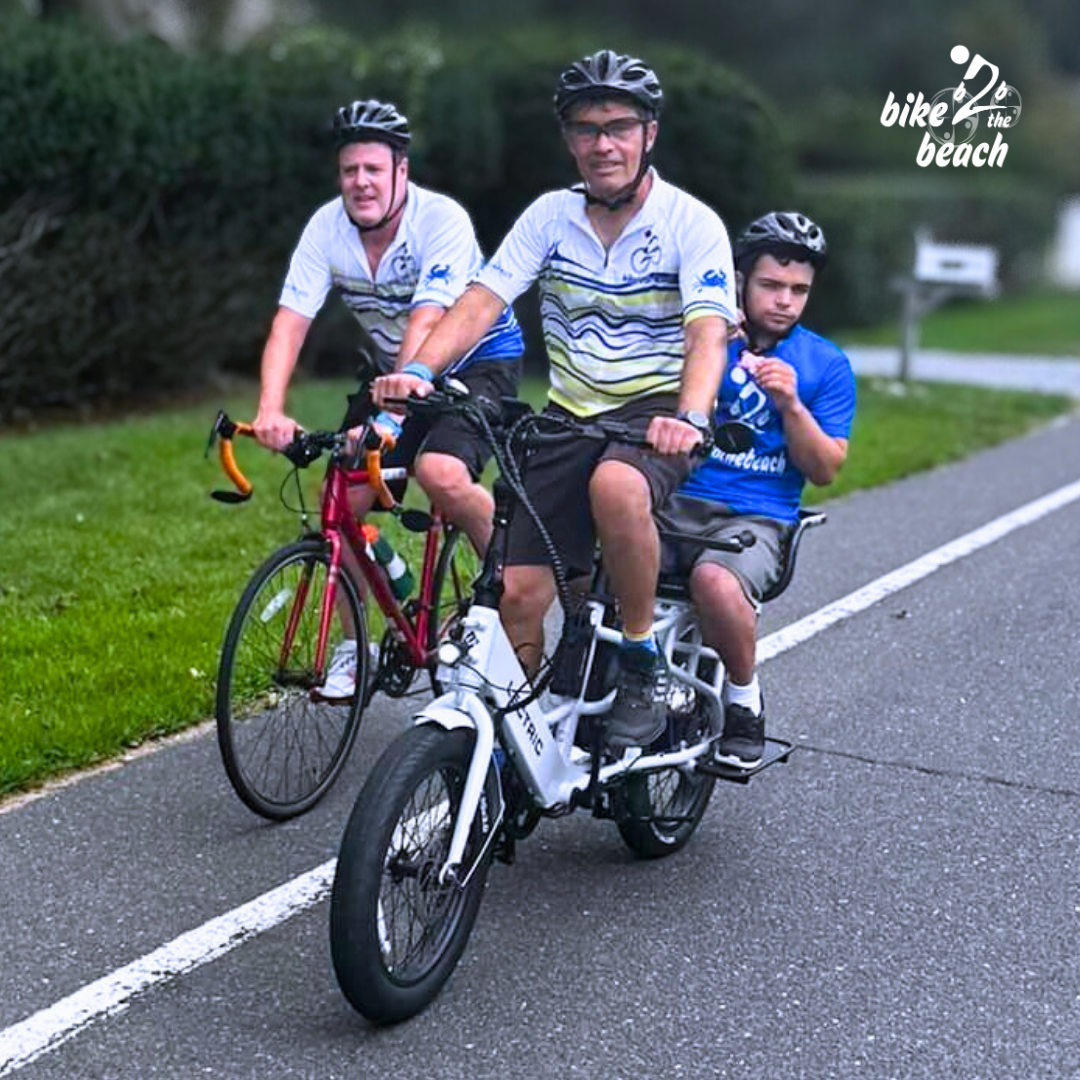
Bike to the Beach offers one customer-specific example. Its community bike rides combine cycling, charitable giving, regional events, and partnerships with local autism and disability organizations. Its revenue model includes participant fundraising, registration fees, corporate sponsorship, and in-kind partnerships. Those streams support a community-centered model, but they should be evaluated as examples rather than recommendations for every nonprofit.
Connect participation to accountable outcomes
Community participation becomes more meaningful when supporters can see what their involvement makes possible. A nonprofit can report the partners it supports, the regions reached, the dollars raised and distributed, and the services those funds help advance. It can also pair those measures with participant averages, testimonials, and case studies. This combination gives donors both scale and human context.
Measurement should remain honest about what is known and what still needs improvement. Bike to the Beach’s impact framework tracks partner organizations, regional goals, dollars raised and distributed, participant averages, testimonials, and case studies, while identifying gaps such as people served, long-term outcomes, and cost per beneficiary. That transparency is useful for any organization reviewing whether fundraising investment is strengthening mission delivery.
For nonprofits building a participation-based model, resources that help teams plan peer-to-peer fundraising can connect volunteers, partners, and supporters around a shared purpose. Clear roles also help leaders engage board members in fundraising without reducing community impact to a single financial ratio.
Explore the Bike to the Beach community to connect sustainable fundraising with local action.
Frequently Asked Questions
What percentage of a nonprofit budget should be fundraising?
There is no universal percentage that fits every nonprofit. Set the amount by reviewing your organization’s stage, revenue mix, fundraising methods, staffing capacity, and expected mission results. The Association of Fundraising Professionals recommends evaluating fundraising cost in context rather than treating one ratio as a rule: AFP explains why fundraising cost varies.
Should fundraising expenses be counted as overhead?
Usually, fundraising is classified with management and general expenses as part of overhead, while direct program expenses are reported separately. Use consistent accounting categories, then explain them clearly so your board and supporters can see how fundraising investment supports future revenue and program work.
How often should a nonprofit review its fundraising budget?
Review actual income and expenses against the approved budget regularly, not only at year-end. A monthly or quarterly review can reveal changing channel performance, staffing needs, cash-flow pressure, or opportunities to adjust the next fundraising test before a small variance becomes a larger planning problem.
What should a board ask before approving fundraising spending?
Ask which revenue goals the investment supports, what costs are fully included, how results will be measured, and what assumptions could change. Also ask how the plan affects donor experience, program capacity, and financial resilience. A clear scenario comparison helps the board evaluate tradeoffs without relying on a single overhead ratio.
Ready to connect fundraising with community impact?
Fundraising decisions become more meaningful when they support clear goals, trusted partners, and the people your nonprofit serves. Explore how Bike to the Beach brings cycling, charitable giving, and local community connections together. Get started by exploring the Bike to the Beach community and consider where a shared mission could strengthen your next fundraising conversation.